Equity Operations

Equity Accounting & Audit Readiness: A Practical Guide for Private Companies

Zohaib Khalid

I

November 3, 2026

An equity balance can reconcile perfectly and still leave an auditor with questions. Here's how private companies can keep their accounting, ownership records, and supporting documentation aligned before those questions arise.

A controller pulls the equity section of the balance sheet ahead of the annual audit. The balances tie to the general ledger, the prior-year numbers roll forward, and the cap table appears current.

‍

Then the auditors request support for a share repurchase completed in June.

‍

Finance has the journal entry and payment confirmation. Legal has the repurchase agreement. The shareholder administrator has updated the shareholder's balance, but the original stock certificate is still listed as outstanding. Nobody is entirely sure whether the board approval was saved with the transaction documents or in a separate corporate records folder.

‍

The accounting may ultimately be correct. The company may have completed the repurchase exactly as intended.

‍

But proving that now requires three departments, several email threads, and a fair amount of detective work.

‍

This is a familiar kind of problem for established private companies. Their equity accounting doesn't necessarily become difficult because they're issuing hundreds of new securities. It becomes difficult because ownership activity accumulates over time, and the information supporting that activity ends up in different places.

‍

A repurchase affects the accounting records, the shareholder register, and possibly the stock certificate records. An option exercise can involve payroll, finance, legal, and equity administration. A family transfer might change the registered holder without changing the company's total shares outstanding.

‍

Each team sees a different part of the transaction.

‍

Equity accounting and audit readiness depend on those parts agreeing with one another.

‍

What equity accounting actually involves

‍

Equity accounting is the process of recording and reporting transactions affecting a company's ownership interests and equity accounts.

‍

For a private corporation, that can include common and preferred stock, additional paid-in capital, retained earnings, treasury stock, stock-based compensation, and other relevant components of shareholders' equity.

‍

The precise accounts depend on the company's structure and applicable accounting framework.

‍

The underlying transactions are often familiar:

  • Issuing shares to investors or employees
  • Repurchasing or redeeming shares
  • Exercising stock options
  • Paying dividends or making other distributions
  • Converting securities or changing the capital structure
  • Recording stock-based compensation
  • Completing stock splits or other equity reorganizations

The accounting treatment isn't always obvious from the transaction description.

‍

A repurchase, for example, may be recorded using treasury stock accounting or another appropriate treatment depending on the circumstances and applicable guidance. A distribution may be treated differently depending on the entity type, the nature of the payment, and the relevant accounting requirements.

‍

An employee option exercise can affect cash, share capital, and additional paid-in capital, while the compensation expense associated with the award may have been recognized over several earlier reporting periods.

‍

These aren't interchangeable events, even if they all change something in the company's equity records.

‍

Finance needs to understand the substance of each transaction, apply the appropriate accounting treatment, and preserve enough supporting information to explain the result.

‍

That last requirement is where audit readiness begins.

‍

The cap table and the general ledger answer different questions

‍

A company's cap table and general ledger should agree where they overlap, but they aren't designed to provide identical information.

‍

The cap table describes ownership: who holds the company's securities, how many they hold, and how those holdings fit into the capital structure.

‍

The general ledger records the financial effects of transactions, including the amounts reported in the company's financial statements.

‍

Consider a private company that issues 100,000 common shares for $1 million.

‍

The ownership records need to show the shares issued, the recipient, the security class, and the relevant transaction details.

‍

The accounting records need to reflect the consideration received and the appropriate allocation among common stock and additional paid-in capital, based on the applicable accounting requirements and the shares' par or stated value.

‍

Both records describe the same transaction, but they do so for different purposes.

‍

Now suppose the company later repurchases 20,000 of those shares.

‍

The cap table needs to reflect what happened to the shareholder's holdings and how the repurchased shares are treated in the company's capitalization records. Finance needs to determine the appropriate accounting treatment and record the financial effects.

‍

If only one set of records is updated, the company has a reconciliation problem.

‍

The same issue arises when a transaction is recorded in both places but with different dates, quantities, or terms.

‍

A cap table can be accurate without containing every accounting detail. The general ledger can be accurate without identifying every shareholder or certificate affected by a transaction.

‍

Neither should be expected to replace the other.

‍

The objective is to make sure they can be reconciled to the same underlying activity.

‍

A clean equity balance doesn't necessarily mean the transaction history is clean

‍

Suppose a company's general ledger reports $5 million in additional paid-in capital.

‍

That balance may be mathematically correct. It may tie to the trial balance and agree with the prior-year financial statements.

‍

An auditor can still ask what transactions contributed to the balance.

‍

How much came from share issuances? How much relates to stock-based compensation? Were any amounts reclassified during the year? Were there modifications, exercises, or repurchases affecting the accounts?

‍

The ending number doesn't answer those questions.

‍

This is why an equity rollforward is so useful.

‍

An equity rollforward starts with the opening balance, identifies activity during the period, and reconciles that activity to the closing balance.

‍

For a private company, the process should cover the relevant equity accounts and be supported by the underlying transactions.

‍

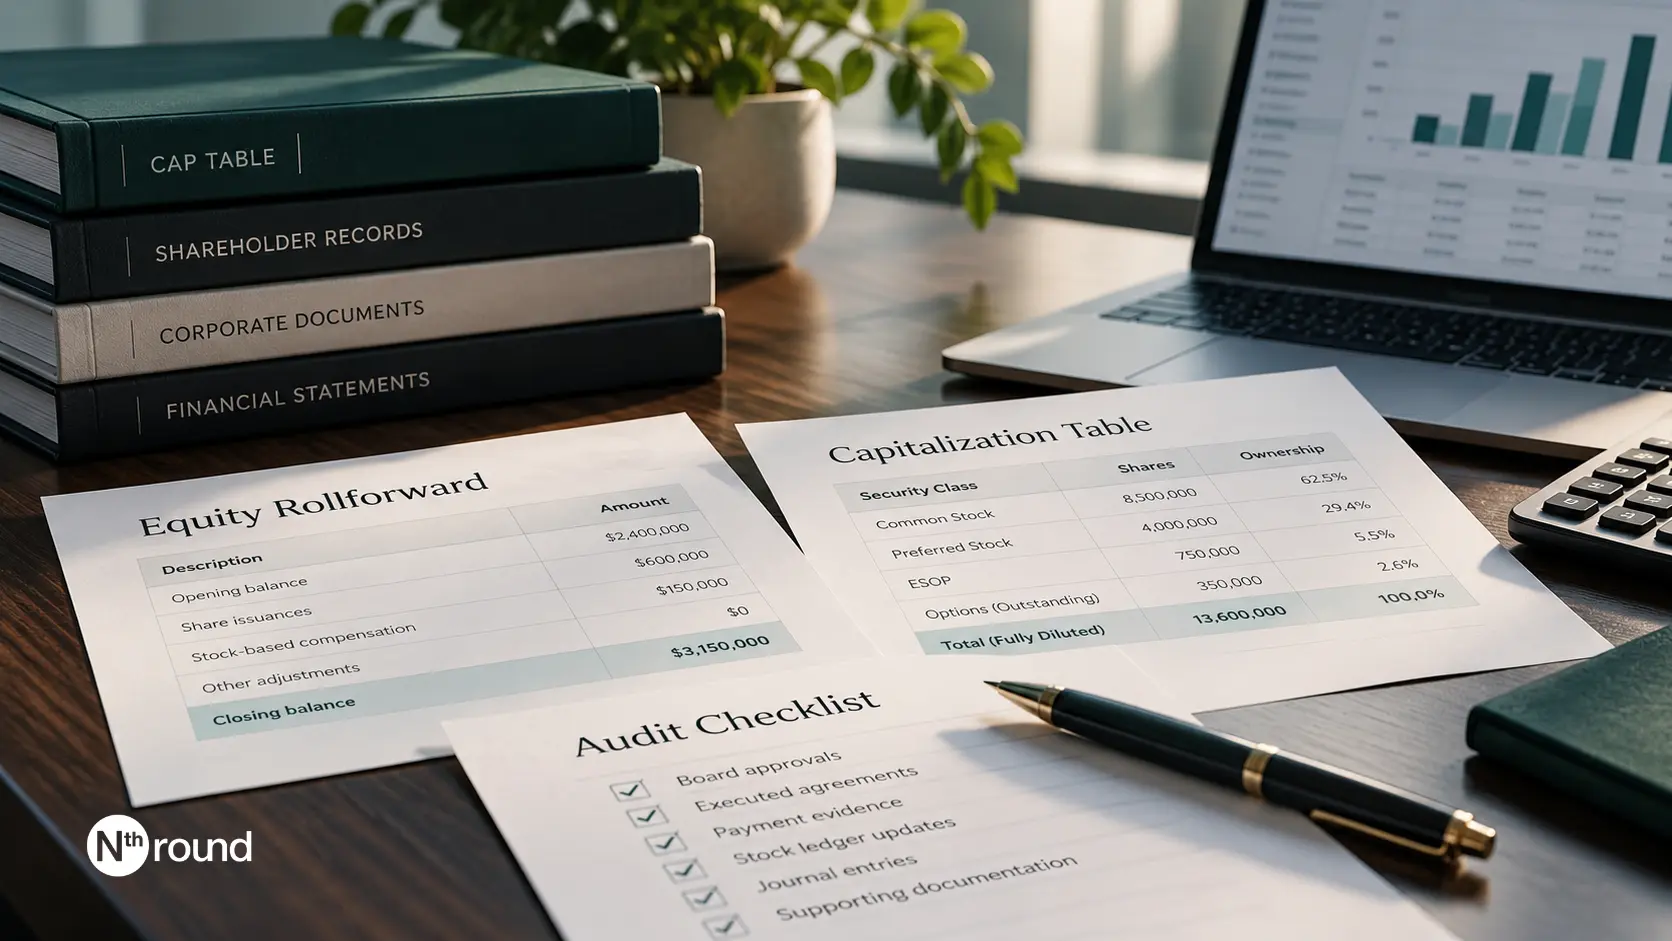
A simplified example might look like this:

‍

EQUITY ACCOUNTING

Equity Rollforward Example

How changes in additional paid-in capital reconcile over a reporting period.

Illustrative
Equity activity Amount
Opening additional paid-in capital $2,400,000
New share issuances credited to APIC $600,000
Stock-based compensation credited to APIC $150,000
Other adjustments $0
Closing additional paid-in capital $3,150,000

Illustrative amounts in USD. Assumes transactions have been appropriately classified and excludes other potential equity activity.

‍

This illustration assumes the transactions have been appropriately classified and excludes other potential equity activity.

‍

The arithmetic is simple. The work is in supporting each line.

‍

Where did the $600,000 come from? Which share issuances does it represent? Do those issuances appear in the stock ledger? Were they properly authorized?

‍

What supports the $150,000 in stock-based compensation? Which awards and expense schedules contributed to it?

‍

If finance can answer those questions from a maintained transaction record, the rollforward becomes a useful audit document.

‍

If the answers require reconstructing activity from bank statements, spreadsheets, and email approvals, the rollforward becomes a year-end project.

‍

Share issuances are easy to record incorrectly when the paperwork and accounting move at different speeds

‍

A private company approves a new share issuance.

‍

The board authorizes the transaction, legal prepares the subscription agreement, and finance expects the investment proceeds.

‍

The shares may be entered into the cap table before the cash arrives. Or the cash may arrive before the final documents are executed. Sometimes the parties agree to an effective date that differs from the date the administrator records the issuance.

‍

Those differences need to be understood rather than ignored.

‍

The appropriate accounting depends on the substance and timing of the transaction, including whether the company has satisfied the relevant requirements for recognizing the issuance and consideration.

‍

For audit purposes, finance may need to support the issuance with board approvals, executed agreements, evidence of consideration, and the corresponding stock ledger entry.

‍

The documents should tell a consistent story.

‍

If the cap table shows shares issued on March 1 but the subscription agreement wasn't executed until March 20, that discrepancy deserves an explanation. It doesn't automatically mean the accounting is wrong, but the company should be able to establish the appropriate effective date and accounting treatment.

‍

The same principle applies to noncash issuances.

‍

Shares issued in exchange for services, assets, or other consideration may require additional valuation and accounting analysis. A cap table entry showing the number of shares issued won't establish the amount that should be recorded in the financial statements.

‍

Repurchases and redemptions deserve particular attention

‍

Share repurchases can be deceptively complicated.

‍

A company agrees to buy back shares from a departing executive. The purchase price is negotiated, the agreement is signed, and finance processes the payment.

‍

From the shareholder's perspective, the transaction may be finished.

‍

For the company, several questions remain.

‍

Were the shares repurchased into treasury, retired, or otherwise treated under the applicable corporate law and accounting guidance? What was the appropriate journal entry? Were the necessary approvals obtained? Did the transaction affect the company's outstanding share count, and were the stock ledger and certificate records updated accordingly?

‍

The distinction between treasury shares and retired shares matters. Shares held in treasury generally remain issued but are not outstanding, while retired shares are no longer issued. The accounting and capitalization records need to reflect the actual treatment.

‍

There can also be complications involving preferred shares, redemption provisions, or arrangements requiring classification outside permanent equity under applicable guidance.

‍

Not every private-company repurchase needs an elaborate accounting memorandum. But unusual terms or significant transactions deserve review before the accounting is finalized.

‍

A practical problem arises when the cash payment and the ownership change are treated as separate tasks.

‍

Finance records the payment. Legal files the agreement. The equity administrator updates the shareholder balance weeks later.

‍

If nobody reconciles those activities, the financial statements and capitalization records may temporarily reflect different positions.

‍

That discrepancy can become harder to explain if the transaction falls near a reporting date.

‍

Stock-based compensation adds another accounting history to maintain

‍

Employee equity awards create a different set of requirements.

‍

Under ASC 718, companies generally recognize compensation cost for share-based payment awards based on the applicable measurement and recognition rules.

‍

For a typical equity-classified employee option award, compensation cost is generally measured using grant-date fair value and recognized over the requisite service period.

‍

That accounting can continue for years after the original grant.

‍

Employees vest. Some leave before vesting. Others exercise options. Award terms may be modified. Performance conditions may be satisfied or fail to be satisfied.

‍

Each event can affect the information used for stock-based compensation accounting.

‍

Consider a company that has accurately recorded every option grant in its cap table but hasn't updated its compensation expense schedule for several employee departures.

‍

The ownership records may show the correct outstanding options. The accounting schedule may still include expense associated with awards that were forfeited.

‍

The issue isn't that the cap table is inaccurate. It's that the accounting depends on information beyond the current award balance.

‍

Finance needs the grant-date valuation support, vesting terms, forfeiture information, modifications, and prior expense recognition history.

‍

We cover those requirements in more detail in our ASC 718 Guide for Private Companies.

‍

For audit readiness, the important point is that the stock-based compensation schedule should reconcile to the underlying award activity and the relevant general ledger accounts.

‍

A correct expense formula won't help much if the award data feeding it is incomplete.

‍

Transfers can change the shareholder register without changing shareholders' equity

‍

Not every ownership change creates a journal entry.

‍

Suppose an individual shareholder transfers 5,000 shares into a family trust.

‍

Assuming this is a transfer between holders rather than a transaction involving the company as issuer or purchaser, the company's total shares outstanding may remain unchanged. Its shareholders' equity accounts may also be unaffected.

‍

But the shareholder register still needs attention.

‍

The company may need to confirm that the transfer is permitted under its governing documents, review the relevant transfer paperwork, and update the registered holder.

‍

This is an important distinction for established private companies, particularly those with family ownership, trusts, estates, and holding entities.

‍

Finance may see no change in the equity accounts and reasonably conclude that no accounting entry is required.

‍

That doesn't mean the administrative work is finished.

‍

The company still needs an accurate record of the legal holder and the history supporting the change.

‍

That information can become relevant to shareholder communications, distributions, voting, and future transactions.

‍

It's one reason ownership administration can't be reduced to accounting entries alone.

‍

What auditors actually need from the equity records

‍

Audit requests vary depending on the company, its accounting framework, and the nature of its equity activity.

‍

Still, the same kinds of questions come up repeatedly.

‍

Auditors may ask for the equity rollforward, current capitalization records, supporting documents for significant transactions, board approvals, stock-based compensation schedules, and reconciliations between the general ledger and the stock ledger.

‍

They may also review the company's accounting policies, financial statement disclosures, and treatment of unusual equity arrangements.

‍

The purpose isn't simply to verify that the cap table adds up.

‍

An audit involves obtaining sufficient appropriate evidence to support the relevant financial statement assertions. For equity, that can include whether transactions occurred, were complete, were recorded in the correct period, were measured and classified appropriately, and were adequately presented and disclosed.

‍

A current ownership spreadsheet doesn't establish all of those things.

‍

Take a share issuance recorded during the year.

‍

An auditor may want to understand the authorization, the agreement, the consideration received, the date of the transaction, and the resulting accounting entry.

‍

Or consider a repurchase.

‍

The auditor may need to examine the repurchase agreement, payment, accounting treatment, and related share records.

‍

If the company can retrieve those items together, the request is manageable.

‍

If each document lives with a different employee and the transaction history has to be pieced together afterward, the same request can consume several days.

‍

The accounting conclusion may not change. The amount of work needed to support it certainly can.

‍

The biggest audit-readiness problem is often timing

‍

Many private companies treat equity reconciliations as something to do during the annual audit.

‍

That's understandable. Equity transactions may be relatively infrequent, and the finance team has more immediate responsibilities throughout the year.

‍

But infrequent activity creates its own problem.

‍

A company might complete only six significant equity transactions in a year. Each one is handled by a different combination of people, with different documents and different accounting consequences.

‍

By December, the details are no longer fresh.

‍

A board approval might be in the corporate minute book. The signed agreement might be in legal's files. A payment confirmation might be attached to a bank reconciliation. The shareholder administrator might have entered the transaction based on an email.

‍

Nothing necessarily went wrong when the transaction happened.

‍

The problem is that nobody assembled the complete record while the information was readily available.

‍

A more reliable approach is to review the accounting and ownership effects when significant transactions occur, then reconcile the records periodically.

‍

For a company with limited equity activity, that may not require a large amount of ongoing work.

‍

It requires consistency.

‍

What a practical equity audit-readiness process looks like

‍

The first step is to establish which records the company considers authoritative for different purposes.

‍

Finance should own the general ledger and accounting conclusions. The stock ledger should accurately reflect the company's registered securities and holders. Legal or the appropriate corporate function should maintain the governing documents and required approvals.

‍

Those responsibilities don't have to sit with one person.

‍

But the company needs a process for making sure the records agree.

‍

When an equity transaction occurs, the people responsible should determine its accounting and ownership effects, collect the necessary documentation, and record the event in the appropriate places.

‍

A periodic reconciliation should then compare the relevant activity and balances.

‍

For many private companies, a workable process includes:

  1. Maintaining an equity rollforward that reconciles opening balances, current-period activity, and closing balances for relevant equity accounts.
  2. Reconciling share activity between the stock ledger, cap table, and records supporting issuances, transfers, repurchases, and other changes.
  3. Reviewing stock-based compensation activity against award records, vesting information, forfeitures, modifications, and accounting schedules.
  4. Preserving transaction support so approvals, agreements, consideration, journal entries, and ownership changes can be traced.
  5. Investigating differences promptly rather than carrying unexplained adjustments into the next reporting period.

The frequency should reflect the company's transaction volume, reporting requirements, and risk.

‍

A business completing several equity transactions each month may need more frequent reconciliations than one with only occasional shareholder activity.

‍

The important thing is that the process exists before the audit begins.

‍

Audit trails are useful only when they preserve the history

‍

A company can keep an accurate current cap table and still struggle to explain historical transactions.

‍

This often happens when administrators update records by replacing the previous information.

‍

A shareholder's balance changes from 10,000 shares to 15,000. The spreadsheet now shows 15,000, but the record doesn't clearly identify the transaction responsible for the increase.

‍

Later, someone discovers the balance should have been 14,000. The administrator corrects it, but the original entry and reason for the correction aren't preserved.

‍

The current number may finally be right.

‍

The history is now difficult to follow.

‍

An auditable equity record should preserve the transaction sequence, relevant dates, supporting documents, and appropriate correction history.

‍

That doesn't mean mistakes can never be fixed. It means the company should be able to explain what was corrected and why.

‍

Our article on maintaining an auditable equity transaction history examines this in more detail.

‍

For finance teams, a reliable history makes reconciliations and audit support considerably easier. Instead of reconstructing the movement between two balances, they can review the transactions that produced it.

‍

When spreadsheets are enough, and when they start creating extra work

‍

Spreadsheets aren't inherently unsuitable for equity accounting.

‍

A private company with a straightforward capital structure, limited transactions, and well-maintained supporting records may be able to manage its reconciliations effectively using spreadsheets.

‍

The problem is rarely the spreadsheet's ability to calculate a balance.

‍

It's the growing amount of information that needs to remain consistent around that balance.

‍

As companies issue more securities, add shareholders, introduce employee equity programs, complete repurchases, or manage transfers involving trusts and estates, the administrative work expands.

‍

Finance may maintain one workbook for equity accounting. Legal may maintain another for shareholder records. The cap table may sit in a separate file, while supporting agreements are distributed across shared drives.

‍

Each record may be reasonably maintained on its own.

‍

The difficulty is keeping them aligned.

‍

This is where dedicated equity and shareholder management software can help organize ownership information, transactions, and supporting documentation.

‍

Nth Round's shareholder management platform is designed for private companies managing ownership records and the administrative activity surrounding them.

‍

It doesn't replace the general ledger, accounting judgment, or external auditors.

‍

The value is in making the ownership information and transaction history more dependable, so finance isn't forced to reconstruct the administrative side of every equity event during the audit.

‍

Audit readiness is built between reporting periods

‍

An annual audit is a poor time to discover that a repurchase agreement was never filed, an option modification wasn't reflected in the expense schedule, or a shareholder transfer was recorded using the wrong date.

‍

Those problems may be fixable. Most are easier to address when the transaction is recent and the people involved still remember the details.

‍

Private companies don't need to turn every equity event into a major compliance exercise. They need to make sure the accounting, ownership records, and supporting documentation are updated as part of the same process.

‍

When that happens, the annual audit becomes a review of records the company already maintains rather than an effort to recreate a year's worth of ownership activity.

‍

And the benefit extends beyond the audit.

‍

Reliable equity records make it easier to respond to shareholder questions, support financial reporting, prepare for due diligence, and handle future transactions without repeatedly revisiting old decisions.

‍

The goal isn't to produce a perfect audit binder once a year.

‍

It's to maintain records that are worth auditing in the first place.
‍

A controller pulls the equity section of the balance sheet ahead of the annual audit. The balances tie to the general ledger, the prior-year numbers roll forward, and the cap table appears current.

‍

Then the auditors request support for a share repurchase completed in June.

‍

Finance has the journal entry and payment confirmation. Legal has the repurchase agreement. The shareholder administrator has updated the shareholder's balance, but the original stock certificate is still listed as outstanding. Nobody is entirely sure whether the board approval was saved with the transaction documents or in a separate corporate records folder.

‍

The accounting may ultimately be correct. The company may have completed the repurchase exactly as intended.

‍

But proving that now requires three departments, several email threads, and a fair amount of detective work.

‍

This is a familiar kind of problem for established private companies. Their equity accounting doesn't necessarily become difficult because they're issuing hundreds of new securities. It becomes difficult because ownership activity accumulates over time, and the information supporting that activity ends up in different places.

‍

A repurchase affects the accounting records, the shareholder register, and possibly the stock certificate records. An option exercise can involve payroll, finance, legal, and equity administration. A family transfer might change the registered holder without changing the company's total shares outstanding.

‍

Each team sees a different part of the transaction.

‍

Equity accounting and audit readiness depend on those parts agreeing with one another.

‍

What equity accounting actually involves

‍

Equity accounting is the process of recording and reporting transactions affecting a company's ownership interests and equity accounts.

‍

For a private corporation, that can include common and preferred stock, additional paid-in capital, retained earnings, treasury stock, stock-based compensation, and other relevant components of shareholders' equity.

‍

The precise accounts depend on the company's structure and applicable accounting framework.

‍

The underlying transactions are often familiar:

The accounting treatment isn't always obvious from the transaction description.

‍

A repurchase, for example, may be recorded using treasury stock accounting or another appropriate treatment depending on the circumstances and applicable guidance. A distribution may be treated differently depending on the entity type, the nature of the payment, and the relevant accounting requirements.

‍

An employee option exercise can affect cash, share capital, and additional paid-in capital, while the compensation expense associated with the award may have been recognized over several earlier reporting periods.

‍

These aren't interchangeable events, even if they all change something in the company's equity records.

‍

Finance needs to understand the substance of each transaction, apply the appropriate accounting treatment, and preserve enough supporting information to explain the result.

‍

That last requirement is where audit readiness begins.

‍

The cap table and the general ledger answer different questions

‍

A company's cap table and general ledger should agree where they overlap, but they aren't designed to provide identical information.

‍

The cap table describes ownership: who holds the company's securities, how many they hold, and how those holdings fit into the capital structure.

‍

The general ledger records the financial effects of transactions, including the amounts reported in the company's financial statements.

‍

Consider a private company that issues 100,000 common shares for $1 million.

‍

The ownership records need to show the shares issued, the recipient, the security class, and the relevant transaction details.

‍

The accounting records need to reflect the consideration received and the appropriate allocation among common stock and additional paid-in capital, based on the applicable accounting requirements and the shares' par or stated value.

‍

Both records describe the same transaction, but they do so for different purposes.

‍

Now suppose the company later repurchases 20,000 of those shares.

‍

The cap table needs to reflect what happened to the shareholder's holdings and how the repurchased shares are treated in the company's capitalization records. Finance needs to determine the appropriate accounting treatment and record the financial effects.

‍

If only one set of records is updated, the company has a reconciliation problem.

‍

The same issue arises when a transaction is recorded in both places but with different dates, quantities, or terms.

‍

A cap table can be accurate without containing every accounting detail. The general ledger can be accurate without identifying every shareholder or certificate affected by a transaction.

‍

Neither should be expected to replace the other.

‍

The objective is to make sure they can be reconciled to the same underlying activity.

‍

A clean equity balance doesn't necessarily mean the transaction history is clean

‍

Suppose a company's general ledger reports $5 million in additional paid-in capital.

‍

That balance may be mathematically correct. It may tie to the trial balance and agree with the prior-year financial statements.

‍

An auditor can still ask what transactions contributed to the balance.

‍

How much came from share issuances? How much relates to stock-based compensation? Were any amounts reclassified during the year? Were there modifications, exercises, or repurchases affecting the accounts?

‍

The ending number doesn't answer those questions.

‍

This is why an equity rollforward is so useful.

‍

An equity rollforward starts with the opening balance, identifies activity during the period, and reconciles that activity to the closing balance.

‍

For a private company, the process should cover the relevant equity accounts and be supported by the underlying transactions.

‍

A simplified example might look like this:

‍

EQUITY ACCOUNTING

Equity Rollforward Example

How changes in additional paid-in capital reconcile over a reporting period.

Illustrative
Equity activity Amount
Opening additional paid-in capital $2,400,000
New share issuances credited to APIC $600,000
Stock-based compensation credited to APIC $150,000
Other adjustments $0
Closing additional paid-in capital $3,150,000

Illustrative amounts in USD. Assumes transactions have been appropriately classified and excludes other potential equity activity.

‍

This illustration assumes the transactions have been appropriately classified and excludes other potential equity activity.

‍

The arithmetic is simple. The work is in supporting each line.

‍

Where did the $600,000 come from? Which share issuances does it represent? Do those issuances appear in the stock ledger? Were they properly authorized?

‍

What supports the $150,000 in stock-based compensation? Which awards and expense schedules contributed to it?

‍

If finance can answer those questions from a maintained transaction record, the rollforward becomes a useful audit document.

‍

If the answers require reconstructing activity from bank statements, spreadsheets, and email approvals, the rollforward becomes a year-end project.

‍

Share issuances are easy to record incorrectly when the paperwork and accounting move at different speeds

‍

A private company approves a new share issuance.

‍

The board authorizes the transaction, legal prepares the subscription agreement, and finance expects the investment proceeds.

‍

The shares may be entered into the cap table before the cash arrives. Or the cash may arrive before the final documents are executed. Sometimes the parties agree to an effective date that differs from the date the administrator records the issuance.

‍

Those differences need to be understood rather than ignored.

‍

The appropriate accounting depends on the substance and timing of the transaction, including whether the company has satisfied the relevant requirements for recognizing the issuance and consideration.

‍

For audit purposes, finance may need to support the issuance with board approvals, executed agreements, evidence of consideration, and the corresponding stock ledger entry.

‍

The documents should tell a consistent story.

‍

If the cap table shows shares issued on March 1 but the subscription agreement wasn't executed until March 20, that discrepancy deserves an explanation. It doesn't automatically mean the accounting is wrong, but the company should be able to establish the appropriate effective date and accounting treatment.

‍

The same principle applies to noncash issuances.

‍

Shares issued in exchange for services, assets, or other consideration may require additional valuation and accounting analysis. A cap table entry showing the number of shares issued won't establish the amount that should be recorded in the financial statements.

‍

Repurchases and redemptions deserve particular attention

‍

Share repurchases can be deceptively complicated.

‍

A company agrees to buy back shares from a departing executive. The purchase price is negotiated, the agreement is signed, and finance processes the payment.

‍

From the shareholder's perspective, the transaction may be finished.

‍

For the company, several questions remain.

‍

Were the shares repurchased into treasury, retired, or otherwise treated under the applicable corporate law and accounting guidance? What was the appropriate journal entry? Were the necessary approvals obtained? Did the transaction affect the company's outstanding share count, and were the stock ledger and certificate records updated accordingly?

‍

The distinction between treasury shares and retired shares matters. Shares held in treasury generally remain issued but are not outstanding, while retired shares are no longer issued. The accounting and capitalization records need to reflect the actual treatment.

‍

There can also be complications involving preferred shares, redemption provisions, or arrangements requiring classification outside permanent equity under applicable guidance.

‍

Not every private-company repurchase needs an elaborate accounting memorandum. But unusual terms or significant transactions deserve review before the accounting is finalized.

‍

A practical problem arises when the cash payment and the ownership change are treated as separate tasks.

‍

Finance records the payment. Legal files the agreement. The equity administrator updates the shareholder balance weeks later.

‍

If nobody reconciles those activities, the financial statements and capitalization records may temporarily reflect different positions.

‍

That discrepancy can become harder to explain if the transaction falls near a reporting date.

‍

Stock-based compensation adds another accounting history to maintain

‍

Employee equity awards create a different set of requirements.

‍

Under ASC 718, companies generally recognize compensation cost for share-based payment awards based on the applicable measurement and recognition rules.

‍

For a typical equity-classified employee option award, compensation cost is generally measured using grant-date fair value and recognized over the requisite service period.

‍

That accounting can continue for years after the original grant.

‍

Employees vest. Some leave before vesting. Others exercise options. Award terms may be modified. Performance conditions may be satisfied or fail to be satisfied.

‍

Each event can affect the information used for stock-based compensation accounting.

‍

Consider a company that has accurately recorded every option grant in its cap table but hasn't updated its compensation expense schedule for several employee departures.

‍

The ownership records may show the correct outstanding options. The accounting schedule may still include expense associated with awards that were forfeited.

‍

The issue isn't that the cap table is inaccurate. It's that the accounting depends on information beyond the current award balance.

‍

Finance needs the grant-date valuation support, vesting terms, forfeiture information, modifications, and prior expense recognition history.

‍

We cover those requirements in more detail in our ASC 718 Guide for Private Companies.

‍

For audit readiness, the important point is that the stock-based compensation schedule should reconcile to the underlying award activity and the relevant general ledger accounts.

‍

A correct expense formula won't help much if the award data feeding it is incomplete.

‍

Transfers can change the shareholder register without changing shareholders' equity

‍

Not every ownership change creates a journal entry.

‍

Suppose an individual shareholder transfers 5,000 shares into a family trust.

‍

Assuming this is a transfer between holders rather than a transaction involving the company as issuer or purchaser, the company's total shares outstanding may remain unchanged. Its shareholders' equity accounts may also be unaffected.

‍

But the shareholder register still needs attention.

‍

The company may need to confirm that the transfer is permitted under its governing documents, review the relevant transfer paperwork, and update the registered holder.

‍

This is an important distinction for established private companies, particularly those with family ownership, trusts, estates, and holding entities.

‍

Finance may see no change in the equity accounts and reasonably conclude that no accounting entry is required.

‍

That doesn't mean the administrative work is finished.

‍

The company still needs an accurate record of the legal holder and the history supporting the change.

‍

That information can become relevant to shareholder communications, distributions, voting, and future transactions.

‍

It's one reason ownership administration can't be reduced to accounting entries alone.

‍

What auditors actually need from the equity records

‍

Audit requests vary depending on the company, its accounting framework, and the nature of its equity activity.

‍

Still, the same kinds of questions come up repeatedly.

‍

Auditors may ask for the equity rollforward, current capitalization records, supporting documents for significant transactions, board approvals, stock-based compensation schedules, and reconciliations between the general ledger and the stock ledger.

‍

They may also review the company's accounting policies, financial statement disclosures, and treatment of unusual equity arrangements.

‍

The purpose isn't simply to verify that the cap table adds up.

‍

An audit involves obtaining sufficient appropriate evidence to support the relevant financial statement assertions. For equity, that can include whether transactions occurred, were complete, were recorded in the correct period, were measured and classified appropriately, and were adequately presented and disclosed.

‍

A current ownership spreadsheet doesn't establish all of those things.

‍

Take a share issuance recorded during the year.

‍

An auditor may want to understand the authorization, the agreement, the consideration received, the date of the transaction, and the resulting accounting entry.

‍

Or consider a repurchase.

‍

The auditor may need to examine the repurchase agreement, payment, accounting treatment, and related share records.

‍

If the company can retrieve those items together, the request is manageable.

‍

If each document lives with a different employee and the transaction history has to be pieced together afterward, the same request can consume several days.

‍

The accounting conclusion may not change. The amount of work needed to support it certainly can.

‍

The biggest audit-readiness problem is often timing

‍

Many private companies treat equity reconciliations as something to do during the annual audit.

‍

That's understandable. Equity transactions may be relatively infrequent, and the finance team has more immediate responsibilities throughout the year.

‍

But infrequent activity creates its own problem.

‍

A company might complete only six significant equity transactions in a year. Each one is handled by a different combination of people, with different documents and different accounting consequences.

‍

By December, the details are no longer fresh.

‍

A board approval might be in the corporate minute book. The signed agreement might be in legal's files. A payment confirmation might be attached to a bank reconciliation. The shareholder administrator might have entered the transaction based on an email.

‍

Nothing necessarily went wrong when the transaction happened.

‍

The problem is that nobody assembled the complete record while the information was readily available.

‍

A more reliable approach is to review the accounting and ownership effects when significant transactions occur, then reconcile the records periodically.

‍

For a company with limited equity activity, that may not require a large amount of ongoing work.

‍

It requires consistency.

‍

What a practical equity audit-readiness process looks like

‍

The first step is to establish which records the company considers authoritative for different purposes.

‍

Finance should own the general ledger and accounting conclusions. The stock ledger should accurately reflect the company's registered securities and holders. Legal or the appropriate corporate function should maintain the governing documents and required approvals.

‍

Those responsibilities don't have to sit with one person.

‍

But the company needs a process for making sure the records agree.

‍

When an equity transaction occurs, the people responsible should determine its accounting and ownership effects, collect the necessary documentation, and record the event in the appropriate places.

‍

A periodic reconciliation should then compare the relevant activity and balances.

‍

For many private companies, a workable process includes:

  1. Maintaining an equity rollforward that reconciles opening balances, current-period activity, and closing balances for relevant equity accounts.
  2. Reconciling share activity between the stock ledger, cap table, and records supporting issuances, transfers, repurchases, and other changes.
  3. Reviewing stock-based compensation activity against award records, vesting information, forfeitures, modifications, and accounting schedules.
  4. Preserving transaction support so approvals, agreements, consideration, journal entries, and ownership changes can be traced.
  5. Investigating differences promptly rather than carrying unexplained adjustments into the next reporting period.

The frequency should reflect the company's transaction volume, reporting requirements, and risk.

‍

A business completing several equity transactions each month may need more frequent reconciliations than one with only occasional shareholder activity.

‍

The important thing is that the process exists before the audit begins.

‍

Audit trails are useful only when they preserve the history

‍

A company can keep an accurate current cap table and still struggle to explain historical transactions.

‍

This often happens when administrators update records by replacing the previous information.

‍

A shareholder's balance changes from 10,000 shares to 15,000. The spreadsheet now shows 15,000, but the record doesn't clearly identify the transaction responsible for the increase.

‍

Later, someone discovers the balance should have been 14,000. The administrator corrects it, but the original entry and reason for the correction aren't preserved.

‍

The current number may finally be right.

‍

The history is now difficult to follow.

‍

An auditable equity record should preserve the transaction sequence, relevant dates, supporting documents, and appropriate correction history.

‍

That doesn't mean mistakes can never be fixed. It means the company should be able to explain what was corrected and why.

‍

Our article on maintaining an auditable equity transaction history examines this in more detail.

‍

For finance teams, a reliable history makes reconciliations and audit support considerably easier. Instead of reconstructing the movement between two balances, they can review the transactions that produced it.

‍

When spreadsheets are enough, and when they start creating extra work

‍

Spreadsheets aren't inherently unsuitable for equity accounting.

‍

A private company with a straightforward capital structure, limited transactions, and well-maintained supporting records may be able to manage its reconciliations effectively using spreadsheets.

‍

The problem is rarely the spreadsheet's ability to calculate a balance.

‍

It's the growing amount of information that needs to remain consistent around that balance.

‍

As companies issue more securities, add shareholders, introduce employee equity programs, complete repurchases, or manage transfers involving trusts and estates, the administrative work expands.

‍

Finance may maintain one workbook for equity accounting. Legal may maintain another for shareholder records. The cap table may sit in a separate file, while supporting agreements are distributed across shared drives.

‍

Each record may be reasonably maintained on its own.

‍

The difficulty is keeping them aligned.

‍

This is where dedicated equity and shareholder management software can help organize ownership information, transactions, and supporting documentation.

‍

Nth Round's shareholder management platform is designed for private companies managing ownership records and the administrative activity surrounding them.

‍

It doesn't replace the general ledger, accounting judgment, or external auditors.

‍

The value is in making the ownership information and transaction history more dependable, so finance isn't forced to reconstruct the administrative side of every equity event during the audit.

‍

Audit readiness is built between reporting periods

‍

An annual audit is a poor time to discover that a repurchase agreement was never filed, an option modification wasn't reflected in the expense schedule, or a shareholder transfer was recorded using the wrong date.

‍

Those problems may be fixable. Most are easier to address when the transaction is recent and the people involved still remember the details.

‍

Private companies don't need to turn every equity event into a major compliance exercise. They need to make sure the accounting, ownership records, and supporting documentation are updated as part of the same process.

‍

When that happens, the annual audit becomes a review of records the company already maintains rather than an effort to recreate a year's worth of ownership activity.

‍

And the benefit extends beyond the audit.

‍

Reliable equity records make it easier to respond to shareholder questions, support financial reporting, prepare for due diligence, and handle future transactions without repeatedly revisiting old decisions.

‍

The goal isn't to produce a perfect audit binder once a year.

‍

It's to maintain records that are worth auditing in the first place.

‍

Frequently Asked Questions

‍

What is equity accounting for a private company?

Equity accounting involves recording and reporting transactions affecting a company's equity accounts, including share issuances, repurchases, dividends, stock-based compensation, and other relevant changes. The specific accounting treatment depends on the company's structure and applicable accounting standards.

‍

What is an equity rollforward?

An equity rollforward reconciles the opening balance of an equity account to its closing balance by identifying activity during the reporting period. It helps finance teams explain changes and support the amounts reported in the financial statements.

‍

How does a cap table relate to equity accounting?

A cap table tracks ownership and capitalization, while the general ledger records the financial effects of transactions. They serve different purposes but should reconcile where their information overlaps.

‍

What equity records do auditors typically request?

Depending on the company and audit scope, auditors may request equity rollforwards, stock ledgers, capitalization records, board approvals, transaction agreements, payment evidence, stock-based compensation schedules, and supporting reconciliations.

‍

Do shareholder transfers always require accounting entries?

No. A transfer between shareholders may change the registered holder without changing the company's total shares outstanding or equity accounts. The company may still need to review and document the transfer and update its shareholder records.

‍

Can private companies use spreadsheets for equity accounting?

Yes. Spreadsheets can be appropriate when transactions are limited and the company maintains effective controls, supporting documentation, and reconciliations. As ownership activity becomes more complex, keeping multiple records aligned may become increasingly difficult.

‍

Does equity management software replace accounting software?

No. Equity management software and accounting systems serve different functions. Equity and shareholder management tools help maintain ownership records and transaction information, while accounting systems record the financial effects of those transactions.

‍